We gave ManageFC clubs a bank. That's either the most useful sentence on this blog or the most dangerous one, depending entirely on what you do in the two minutes after reading it. Here's the bank, exactly as we run it.
How much it lends
The bank lends on your club's scale. At the reference level — division 3 of a strong football nation — a single loan runs from 100,000 to 50,000,000. A division-10 club in the same country can borrow from about 100 to 53,000, a division-1 club from about 1.6M to 790M. The Bank tab shows your own sizes; the figures below are at the reference level.
The two rates
The interest depends only on how big the loan is within your range — never on your reputation or your league position:
- Up to a fifth of your range (10,000,000 at the reference level) — 2% per period, charged six times: 12% total on top of the principal.
- Above it — 3% per period, charged six times: 18% total.
That's a genuine cliff, and it's deliberate. Borrowing exactly 10,000,000 costs you 1,200,000 in interest. Borrowing 10,100,000 — ever so slightly more — costs 1,818,000. Crossing the line by a hundred thousand costs you more than half a million extra. If you're close to the line, stay under it.
The instalments
We split the total into 26 weekly payments, taken every week until the loan is cleared, so it is gone within half a year. A few anchors at the reference level:
- 1,000,000 → 1,120,000 total → 43,077 per week
- 5,000,000 → 5,600,000 total → 215,385 per week
- 10,000,000 → 11,200,000 total → 430,769 per week
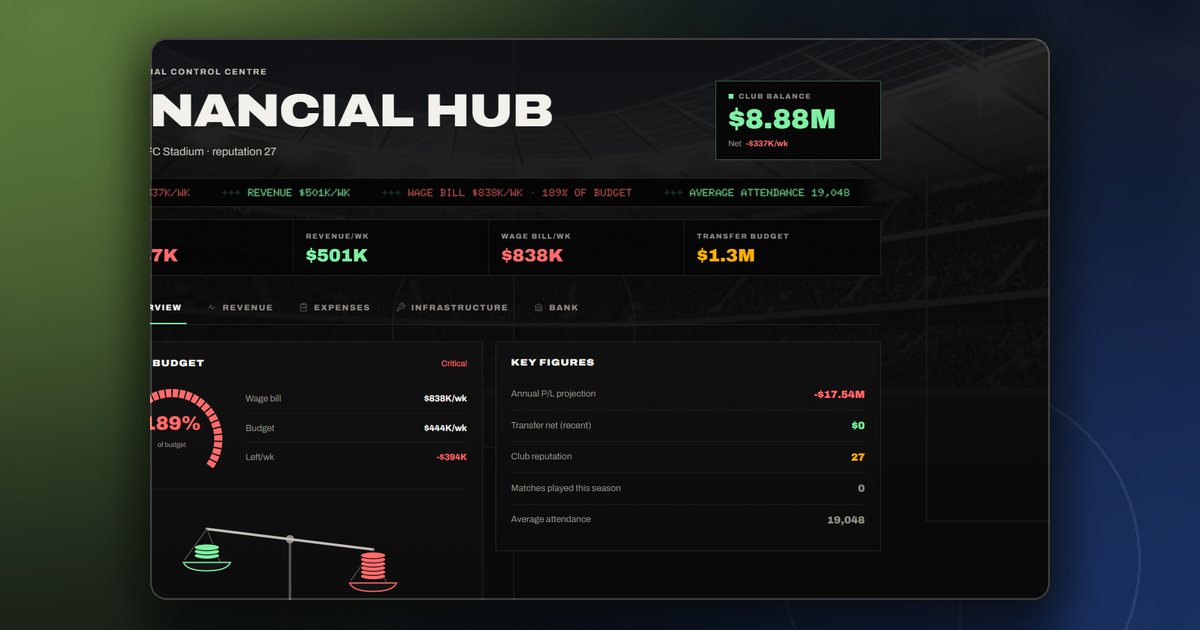
For a club of that size, whose ordinary income is about 190,000 a week, the weekly instalment on the first loan is already a fifth of everything it earns. Size the loan against your weekly income, not against the cash it puts in the bank.
And one rule that shapes everything: the club can carry one loan at a time. Until it's repaid, no second application. So size the loan for the whole move you're funding, not the first half of it. The bank will also refuse a club that is already over its debt limit.
When it makes sense — and when it never does
A loan is a lever for one specific, quantified move. The two cases we'd defend:
- A young player whose resale value will clearly clear principal plus interest before the 26 weeks are out.
- A promotion push where the division prize and the league money jump alone repay the loan. Moving from division 3 to division 2 almost quadruples your weekly league money — that's a loan-sized difference, permanently.
Loans to cover wages, or to plug a budget gap, are almost always a mistake. You're trading a moment of comfort for a twenty-six week squeeze, and it does not end there: a club whose balance stays below zero pays interest on the overdraft, and a full year in the red ends the career.
Check the alternative first
Before borrowing, open the squad and look for saleable depth. A transfer fee is interest-free and permanent, and the market is open in the summer window and again in January. If you've got a 27-year-old backup on decent wages who's worth a fee to somebody, that's a cheaper loan than the bank's.
The full worked numbers are in the wiki's Loans and club debt article, and the finance guide covers the weekly income the instalment has to live inside. If a signing is on the horizon, read where the money comes from first — we'd treat the bank as the last resort, not the first button — and the weekly bill the instalment has to survive is broken down in Wages.
Comments
No comments yet — start the conversation.